Check Point Software NASDAQ: CHKP is in the midst of a major turnaround, gaining traction, as reflected in its stock price.
Check Point Software Technologies Today
CHKP
Check Point Software Technologies
$148.43 +1.85 (+1.26%) As of 12:13 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $112.23
▼
$202.24 - P/E Ratio
- 17.86
- Price Target
- $151.32
The turnaround is more of a shift from legacy product sales to new-age, cloud-based cybersecurity subscriptions and the inflection point is at hand. While Q3 revenue came in light, contracting 1.1% year over year, management called it the low point of the cycle and expects improvement and growth in the quarters ahead.
As it stands, the legacy business accounts for less than 20% of Q3 revenue and will have a diminishing impact on results, regardless of growth. Growth is solid in the cloud-based segment. Q3 results reveal an 11% increase, with management highlighting improving forward-looking indicators and an optimistic outlook.
Check Point Software Is a Cash Flow Machine
Tepid as the Q3 results were, including margin contraction, the news wasn't all bad. Key details included relative strengths, such as better-than-forecast earnings despite top-line weakness, and sufficient cash flow to sustain the capital return. Operating cash flow margin came in at 39%, providing $258 million in free cash flow, insufficient to cover the capital return on its own but supported by trailing 12-month (TTM) activity.
Balance sheet highlights reflect the aggressive buybacks. Cash is down but offset by higher long-term assets, lower liabilities, and a smaller share count. Equity fell but, again, is offset by TTM activity, which includes a 6.9% reduction in share count and the capacity to sustain future buybacks. The company is at an inflection point, and margin recovery is also anticipated, with earnings expected to grow at an accelerated pace.
Even with security as a central component of the AI ecosystem, Check Point Software is expected to grow at a modest mid-single-digit pace in the upcoming years, compared to higher double-digit growth rates for most competitors. Meanwhile, earnings growth is tied to share buybacks, which isn’t a bad thing but not the same as structural improvements in profitability.
Analysts and Institutions Show Confidence in Check Point's Turnaround
The question is whether sell-side interests such as analysts and institutions are buying into the turnaround story, and they are. Analysts and institutions reflect a strong conviction, with 27 active analyst ratings on MarketBeat and institutions owning nearly 99% of the shares.
While analysts reset price targets over the past year, leading the market into its correction, Q3 activity reveals a rebound in analyst sentiment that is gaining momentum in Q4. Initial responses to Q3 results included caution, but with a focus on strong subscription sales and the expected inflection to growth in the upcoming quarter. Another key detail is Check Point's remaining performance obligation, which grew by 5% in the quarter, underpinned by next-gen products.
Check Point Software Has Catalysts to Drive Share Prices
Check Point Software has several catalysts that could drive share prices, centered on subscription growth. Improving subscription growth provides visibility into future cash flow and capital returns, and the adoption of new products suggests that strength will be sustained.
New products include AI-specific tools to secure networks, agents, and data centers, as well as aggressive price increases intended to restore margins. A key differentiator between Check Point and other cybersecurity providers is the starting point of its architecture: user-supported hardware or capacity, which it's absorbing in the cloud.
Short-Sellers Aren’t a Risk for CHKP Stock
While Check Point Software has risks, short selling isn’t among them. While short interest is mildly elevated at approximately 7.5%, it is likely tied to institutional hedging, given high institutional ownership, rather than outright bearishness. Chart price action reflects strong institutional support, with the market establishing a solid base soon after hitting the SaaS-Pocalypse bottom earlier this year.
Q4’s narrative is that this market has begun to perk up after reestablishing confidence in the software industry outlook and amid a reversal. Post-release action shows support at the short- and mid-term exponential moving averages, indicating renewed interest and bullish behavior among short-term investors, traders, and speculators.
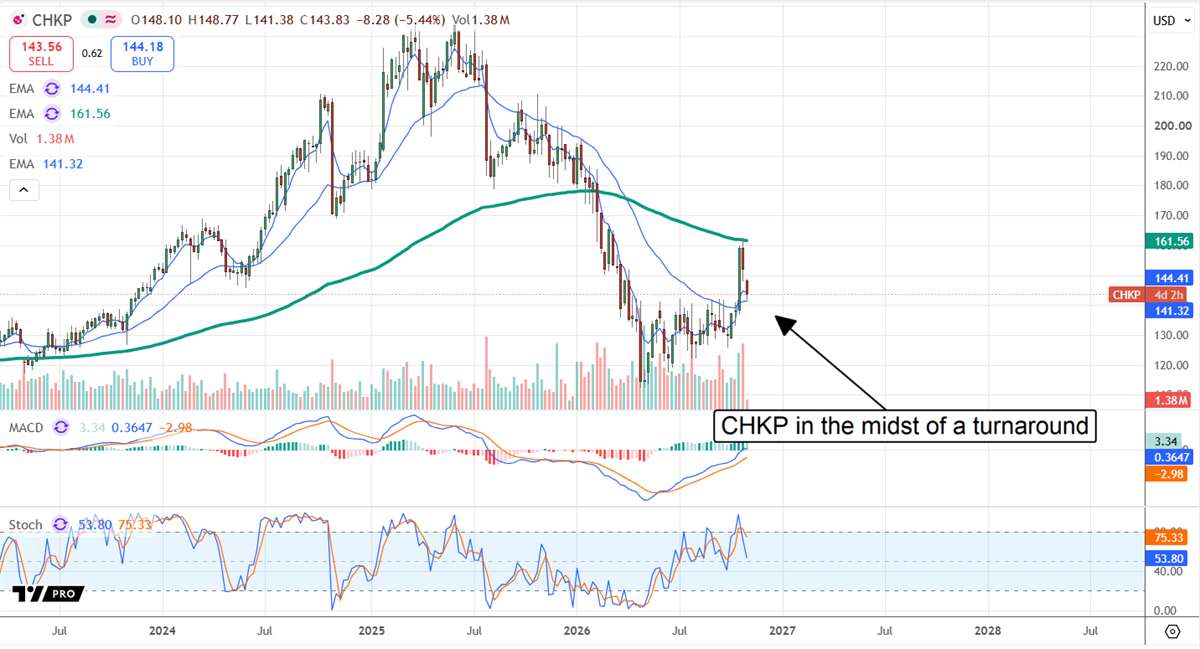
The market got the timing of the turnaround and the drag from legacy operations wrong. Check Point's turnaround is taking longer than expected, which warrants selling the news but not giving up hope. Trading at 14x current-year earnings, the market is pricing in a no-growth, no-cash-flow scenario, which is far from reality. Cybersecurity peers trade at much higher multiples; industry leader Palo Alto Networks NASDAQ: PANW trades at over 100x earnings, suggesting a robust rebound lies ahead and only needs time to unfold.
The biggest risk is execution, but it appears to be progressing well despite the headwinds. Headwinds center on the company’s Israel-based operations, regional conflict, and geopolitical issues tied to tariffs and supply chains.
Before you consider Check Point Software Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Check Point Software Technologies wasn't on the list.
While Check Point Software Technologies currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Nuclear energy is entering a new growth cycle as rising power demand, expanding data centers, and renewed policy support bring the sector back into focus. After strong gains in recent years, the most impactful phase of nuclear investment may still be ahead. This report highlights seven nuclear energy stocks positioned across the value chain—combining near-term revenue with long-term upside as next-generation technologies scale. Click the link below to unlock the full list.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
