BJ's Wholesale Club Today
BJ
BJ's Wholesale Club
$104.89 -5.86 (-5.29%) As of 11/20/2026 03:59 PM Eastern
- 52-Week Range
- $83.21
▼
$113.35 - P/E Ratio
- 20.37
- Price Target
- $106.81
BJ’s Wholesale Club NYSE: BJ pulled back following its Q3 release, opening another entry point for long-term-oriented investors. Margin compression and the impact of a one-time settlement on earnings were the triggers, and the margin pressure was largely expected given the company’s history, strategy, and growth. While near-term headwinds have traders focused on the negative, investors can take advantage of the price weakness to build positions. The market may be overreacting to one-offs, ignoring the core strength and potential for margin recovery in upcoming quarters.
BJ’s investment thesis rests on its growth, valuation, and strategic shift. The company is on track to sustain a mid-to-high single-digit compound annual growth rate over the next five to six years, in line with the industry, and is likely to outperform because of aggressive store-count growth. BJ’s targets nearly 30 stores across 2027 and 2028, an approximate 5% annualized increase compared to the 2026 store count.
BJ’s Wholesale Club's valuation is about 20x current-year earnings, a discount compared to membership club peers, and 16x the 2031 forecast, suggesting 50% to 100% upside over the next few years. Triggers for the move include the growth (not to sound like a broken record) and the strategy shift, which targets a sub-1x leverage ratio and investment-grade credit ratings.
BJ’s Strong Q3 Overshadowed by Margin Compression
BJ’s had a solid Q3, but one-offs are in play that, when backed out, left the market wanting more. The headline $6.283 billion in total revenue isn’t the problem; it grew 17.5%, beating consensus by more than 5%. The problem is the merchandise gross margin, which contracted by approximately 1.7 percentage points due to BJ’s 42nd birthday celebration, with added spending and consumer discounts. Investors should note that the birthday-related costs won't recur, and many other metrics are bullish, starting with top-line performance.
Revenue growth came from a combination of comp store growth, membership, and store count. The company opened two new stores and five new gas stations in the quarter, driving a 5.45% year-over-year (YOY) increase in store count, and membership fee income grew 9.5%. Membership fee income growth is tied to new member acquisition, retention, and tier penetration, suggesting strengths will continue in upcoming quarters. Digital is another driver, up 38% YOY and 69% on a two-year stacked basis.
Margin is mixed, with a one-off juicing the results: operating income, net income, and adjusted net income all improved by more than 40 percent, outpacing top-line growth by more than 23 percentage points because of a one-time legal settlement. However, merchandise margin contracted, and earnings excluding the settlement were below expectations.
Guidance Is a Hurdle in Q4: May Limit Upside Until 2027
Guidance is another detail capping gains in late 2026. Execs improved the comp store and adjusted earnings growth forecasts, but revenue improvement is marginal, and the earnings per share (EPS) lift includes the Q3 windfall. The takeaway is that underlying earnings guidance was diminished despite the headline increase, and may foreshadow weakness in the current quarter. Factors suggesting BJ’s will outperform guidance include comp store momentum, with sales accelerating sequentially in 2026; member count and tier mix; and strength in digitally enabled channels. Industry forecasts expect holiday season sales to accelerate to approximately 5% this year, led by a double-digit gain in digital.
BJ's Wholesale Club Stock Forecast Today
12-Month Stock Price Forecast:$106.811.83% UpsideHoldBased on 20 Analyst Ratings | Current Price | $104.89 |
|---|
| High Forecast | $123.00 |
|---|
| Average Forecast | $106.81 |
|---|
| Low Forecast | $90.00 |
|---|
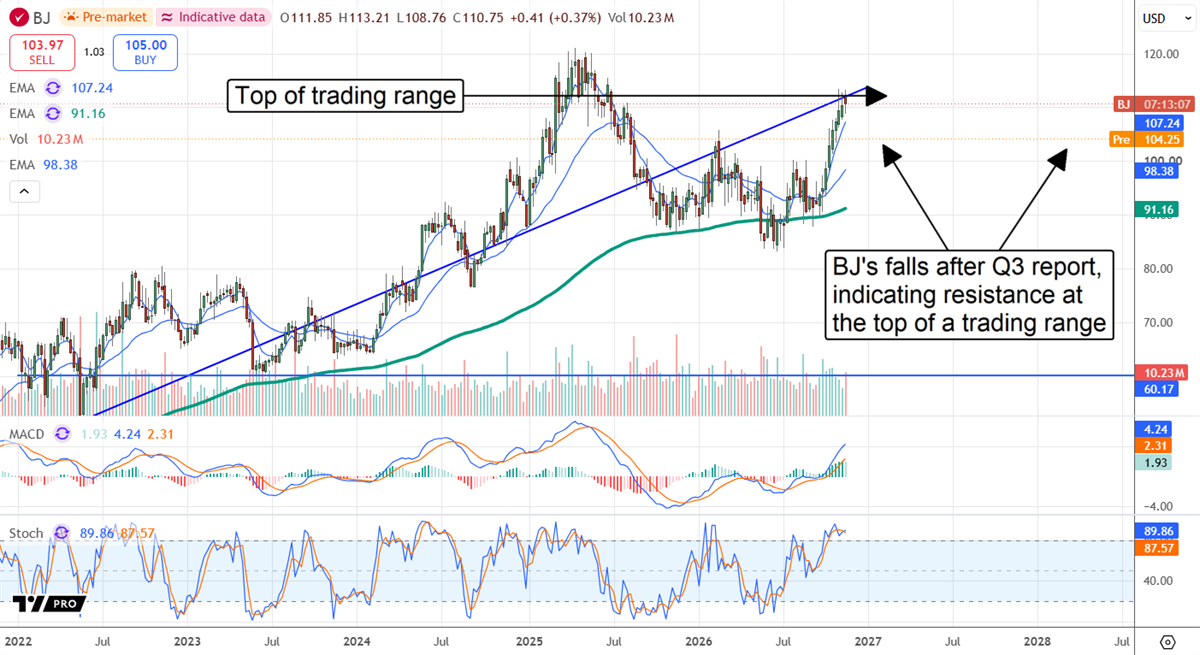
BJ's Wholesale Club Stock Forecast DetailsAnalysts and institutional trends are among Q4’s risks. Both groups reflect confidence in the long-term investment thesis: 21 analysts give the stock a consensus Hold rating, and institutions own 98% of the shares, but upside is limited. The consensus price target is up versus the prior quarter but relatively flat over the past year, assuming fair value near pre-release price levels. The best-case scenario is that analysts reaffirm their ratings, which seems unlikely given the margin weakness. The more likely scenario is that the group shifts into a wait-and-see posture, potentially lowering price targets while sitting on the sidelines.
The institutional group is the bigger risk, as it controls nearly 100% of the market. The group has bought on balance over the trailing 12 months but shifted to distribution ahead of the report, which is unlikely to trigger a bullish response. For investors, this means BJ’s upside is likely capped at or near $110, and a move to the lower end of its trading range is likely. The range’s low end is near $90 and appears firm, based on prior price action.
A move to $90 could trigger a rebound, but investors should wait for the market’s signal before committing capital. Short sellers are not a problem at this time, but the higher-than-average 6.5% short interest remains notable despite declining recently, another warning sign that BJ’s price is capped for now.
Before you consider BJ's Wholesale Club, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and BJ's Wholesale Club wasn't on the list.
While BJ's Wholesale Club currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
