NU Today
$13.03 +1.20 (+10.14%) As of 02:46 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $11.20
▼
$18.98 - P/E Ratio
- 17.64
- Price Target
- $18.25
Nu Holdings Ltd. NYSE: NU delivered its third-quarter earnings report after the market closed on Nov. 12. The highlight was net income that reached a record $1.09 billion, which marked the digital bank's second straight billion-dollar quarter.
Net income was also up 31% year over year on a foreign exchange-neutral (FXN) basis. Gross revenue on the company's managerial basis climbed 37% FXN to $6.26 billion. Return on equity (ROE) was 32%.
Heading into the report, NU wasn't trading like a company heading into a record quarter. Shares closed at $11.83 on Nov. 12, down about 4%. That left NU close to its 52-week low of $11.20, and far below its $18.98 high. Shares initially rebounded following the earnings release.
Several pressures on NU stock since August weren't rooted directly in the company's fundamentals. Deal speculation, Brazil's presidential election, and fund outflows contributed to the weakness.
That meant the Q3 report was the company's first chance to address the key question on investors' minds. Is Nu a Brazil macro bet, or a high-return compounder that happens to be headquartered there? The report largely supports the compounder case. It also gives skeptics one fair talking point: credit quality.
What the Q3 Numbers Say About the Business
Nu added 16 million customers over the past year to reach 143 million. Monthly revenue per active customer (ARPAC) rose 21% FXN to $17.70. The monthly cost to serve each customer was about $1.10.
That spread is what makes the model work. Nu’s efficiency ratio improved to 19.3% from 20.3% a year earlier. Lower is better, and many traditional banks run far higher.
The balance sheet grew alongside earnings:
Credit portfolio: $41.6 billion, up 33% FXN year over year.
Deposits: $47.5 billion, up 19% FXN, at a cost of 87% of interbank rates.
Capital position: $9.9 billion, including $3.6 billion of holding company cash and securities.
Loan-to-deposit ratio: 57%, leaving room to keep lending.
Growth outside Brazil is also gaining scale. Nu Mexico now operates as a licensed bank, with 16.6 million customers, up 27%. Nu Colombia grew customers 62% to 6.1 million, and its credit portfolio jumped 80% FXN.
However, the company's Brazil business is also growing. Nu originated a record volume of unsecured personal loans, up 28%. Its new Croma tier, aimed at higher earners, approached one million customers within three months.
The Number the Market May Focus On
Credit is the one area where the fundamentals do raise questions. The 90-day-plus non-performing loan (NPL) ratio rose to 7.3%. That’s up from 6.9% last quarter and 6.7% a year ago. It’s the highest reading in the deck’s three-year history.
NU Stock Forecast Today
12-Month Stock Price Forecast:$18.2539.96% UpsideModerate BuyBased on 16 Analyst Ratings | Current Price | $13.04 |
|---|
| High Forecast | $23.00 |
|---|
| Average Forecast | $18.25 |
|---|
| Low Forecast | $10.00 |
|---|
NU Stock Forecast DetailsThat metric hasn't always dictated the stock's direction. After Q2, shares rallied despite the ratio reaching 6.9%. Interest-earning loans now make up 61% of the portfolio, up from 44% three years ago. Those loans carry higher delinquency rates by design. Measured against that portfolio, the 90-day NPL ratio is 12.1%. That falls within its 11% to 13.3% range since 2023.
Early delinquencies also stayed steady. The 15-to-90-day NPL ratio was 4.9%, essentially flat from Q2.
Nu attributes 13 basis points of pressure on early delinquencies and a $135 million increase in expected credit loss allowances to “intentional risk expansions.” Coverage of 90-day NPLs slipped to 234% from 244%. The risk-adjusted net interest margin eased to 12.1% from 12.4%. Excluding one-time items, however, the recurring margin improved.
None of this necessarily points to a credit problem today. However, it does mean Nu is taking on more risk to grow, and investors will watch whether the returns justify it.
A Tax Tailwind Worth Noting
Headline profit got some help below the operating line. Under International Financial Reporting Standards (IFRS), pretax profit grew 21% to $1.35 billion. Income taxes fell to $259 million from $334 million a year earlier.
The implied tax rate dropped to about 19% from roughly 30%. That helped net income grow faster than pretax profit. Nu’s managerial view, which adjusts for tax-equivalency items, shows pretax earnings up 41%. Either way, investors should ask whether the lower rate is repeatable.
Spending also rose for growth. On a managerial basis, marketing expenses roughly doubled to $116 million, reflecting Mexico’s bank launch campaign and the global rollout. That spending is discretionary, and it sets up future growth.
NU Stock Chart: Weak Momentum, But Not Yet Repaired
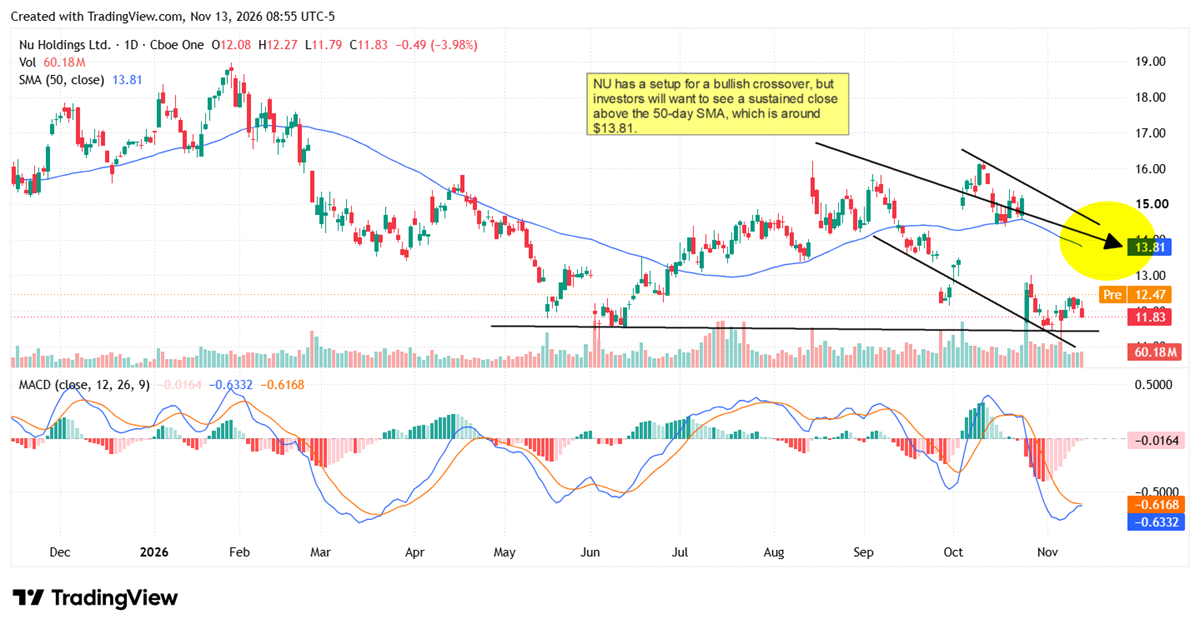
The technical picture shows damage that hasn’t been repaired. NU trades well below its 50-day simple moving average (SMA), which sits near $13.81 and is still falling. The stock hasn’t closed above that line since the late-October election gap.
That gap is the key overhead level. Shares broke down from roughly $14.50 to about $13 in late October, and the gap remains open. The $13 area is the first test, followed by the 50-day SMA.
Momentum is trying to turn. The MACD line sits near -0.63, just below its signal line, and the histogram has shrunk to nearly zero. A bullish crossover looks close. But both lines remain well below zero, which still signals a downtrend.
Support sits at the 52-week low of $11.20, with the June low near $11.60 just above it. A move toward $12.50 would put NU back in the middle of that range. It would not change the trend.
For the setup to improve, NU needs to reclaim $13 on strong volume. The election-day sell-off came on roughly 340 million shares. A recovery that matters will likely need heavy buying, too.
How to Value NU's 32% ROE
Near $12.50, NU’s market value is roughly $60 billion. Q3 profit annualizes to about $4.4 billion. That puts NU near 14 times run-rate earnings for a bank earning a 32% ROE.
The macro discount is real. Brazil’s policy direction, rates, and currency all affect Nu. But the Q3 business did not behave like a company in trouble. Revenue, customers, deposits, and profits all hit records.
The market is pricing NU on Brazil’s headlines. The income statement says it’s a compounder with a credit trend to monitor.
Before you consider NU, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NU wasn't on the list.
While NU currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Nuclear energy is entering a new growth cycle as rising power demand, expanding data centers, and renewed policy support bring the sector back into focus. After strong gains in recent years, the most impactful phase of nuclear investment may still be ahead. This report highlights seven nuclear energy stocks positioned across the value chain—combining near-term revenue with long-term upside as next-generation technologies scale. Click the link below to unlock the full list.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
