The housing market's slowdown is creating a divide in the building-materials industry. While homebuilders struggle to attract buyers, companies that supply materials for repairs, renovations, and replacement projects have a different opportunity to capture demand.
The gap between new and existing mortgage rates helps explain why. Mortgage rates have risen back above 7%, which not only prices out first-time buyers but also makes moving financially unfeasible. Federal housing data analysis showed that while the number of homeowners with mortgage rates above 6% grew in Q2 2026, only 22.5% of total mortgages have rates of 6% or higher. The average rate on outstanding mortgages is 4.4%, so most Americans have little incentive to move unless there’s a catalyst like children or a new job.
The pressure is evident in the new-home market. The NAHB/Wells Fargo Housing Market Index fell to 29 in October, its lowest reading since June 2012, while, homebuilders like D.R. Horton Inc. NYSE: DHI continue offering costly mortgage-rate buydowns and other incentives to attract buyers, putting additional pressure on their margins.
Instead of moving, some homeowners are choosing to invest in their existing properties. Combined with ongoing demand for commercial property maintenance and replacement projects, that creates opportunities for building-materials suppliers. Three stocks in particular are showing momentum that many homebuilders lack.
Masco: The Cleanest Repair and Remodel Play
Masco Today
$84.72 +0.24 (+0.28%) As of 11/13/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $58.16
▼
$87.86 - Dividend Yield
- 1.51%
- P/E Ratio
- 18.34
- Price Target
- $81.82
One of the biggest beneficiaries of homeowner upgrades is Masco Corp. NYSE: MAS, which manufactures faucets and fixtures under the Delta, Peerless, and Hansgrohe brands, and paint under Behr and Kilz.
Unlike most companies in the homebuilding industry, Masco is actually growing margin and raising guidance, and the stock has responded with a year-to-date (YTD) gain of more than 30%.
Masco reported Q3 2026 earnings on Oct. 28 and posted a top- and bottom-line beat, but the outlook was what really impressed the market.
Revenue grew 3% year over year (YOY) and operating profit surged 13% YOY, both above analysts’ estimates, and gross margins expanded 2.4 basis points to 36.6%. Notably, these results were relatively free of one-time items, with pricing, cost savings, and lower year-over-year tariff costs helping drive profit growth
Management raised full-year 2026 earnings per share (EPS) guidance to $4.65 to $4.75 and operating margin outlook to 18% to 18.5%, despite anticipating inflation from copper, oil, and freight in the coming period.
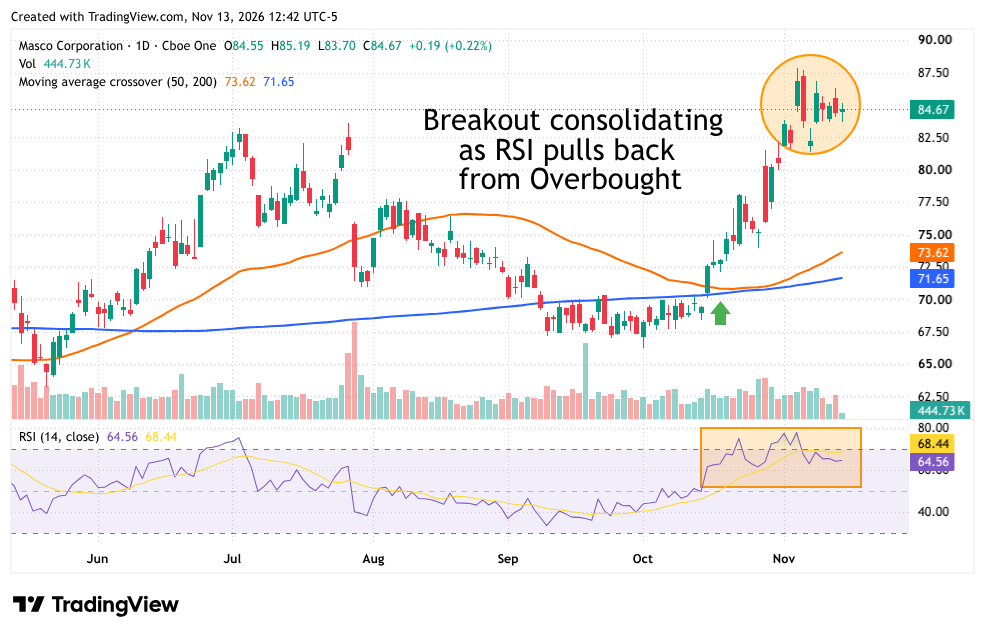
The stock finally broke the previous 2024 all-time high earlier this month, and now appears to be consolidating ahead of its next move. The price is firmly above the 50-day and 200-day moving averages, and the Relative Strength Index (RSI) has retreated from overbought territory. Unless component inflation comes in higher than expected, Masco has both fundamental and technical tailwinds behind it.
Carlisle: Businesses Need New Roofs Too
Carlisle Companies Today
CSL
Carlisle Companies
$396.21 +3.62 (+0.92%) As of 11/13/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $293.43
▼
$432.91 - Dividend Yield
- 1.26%
- P/E Ratio
- 22.40
- Price Target
- $406.43
Carlisle Companies Inc. NYSE: CSL doesn’t traditionally sell into the residential home markets.
Instead, it focuses on commercial roofing and insulation, and many business owners are choosing to replace roofs rather than finance new construction.
The roofing segment has been one of the company’s leaders for decades, and its revenue is still growing strongly.
Carlisle also beat estimates during its Q3 2026 report on Oct. 28, with Construction Materials (the roofing segment) revenue up 8% YOY. Adjusted EPS hit a third-quarter record of $5.92 despite material and freight inflation cutting into margins, and management expects costs to normalize in 2027.
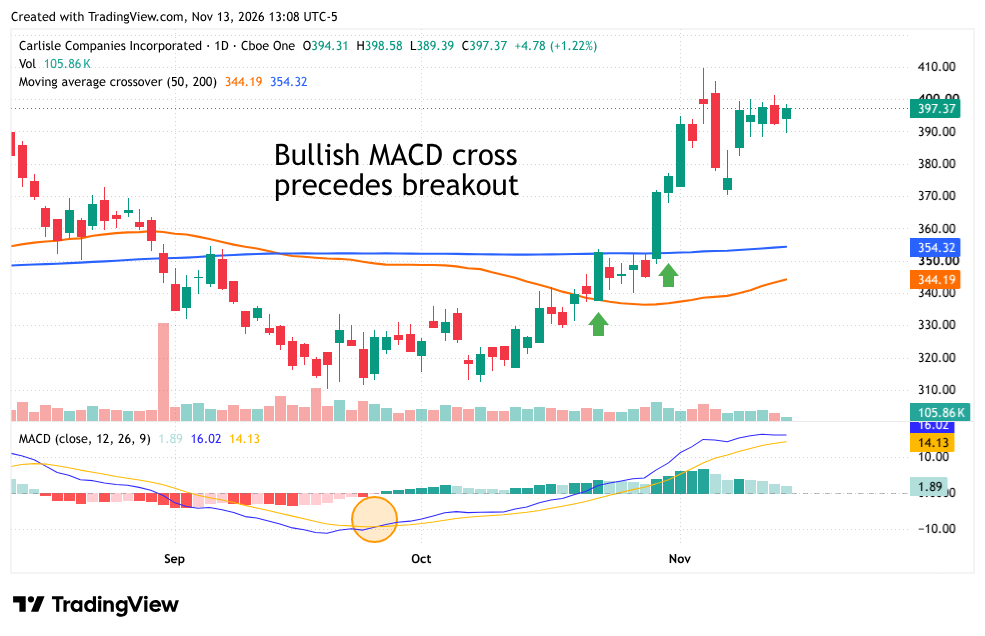
A bullish Moving Average Convergence Divergence (MACD) cross in September foretold the recent breakout, which took the price back above the 50-day and 200-day moving averages. The stock is now up nearly 25% on the year, with nearly all gains coming in the last 30 days. Momentum is strong, and the technical signals point to more upside ahead.
James Hardie: Taking Market Share Through Mergers and Acquisitions
James Hardie Industries Today
JHX
James Hardie Industries
$27.82 +0.26 (+0.95%) As of 11/13/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $16.46
▼
$31.43 - P/E Ratio
- 45.61
- Price Target
- $33.44
James Hardie Industries PLC NYSE: JHX is a global building materials firm that has expanded into the home remodeling space with its TimberTech decking and fiber-cement siding through its 2025 AZEK acquisition.
Homeowners looking to redo a patio or add an exterior fixture will likely seek these products and services, and the company is ahead of schedule in deleveraging from its mergers.
The company reported fiscal Q2 2027 results on Nov. 5, also beating top- and bottom-line estimates with YOY sales growth of 24% from continuing operations.
Adjusted EBITDA margin expanded 450 basis points to 31.8%, and the company reaffirmed its full-year fiscal 2027 sales guidance while raising free cash flow guidance. By segment, Siding & Trim sales grew 15%, and Deck, Rail & Accessories sales grew 51%, with approximately 14 percentage points coming from underlying growth.
However, the Q3 sales guide was below expectations, and the company is priced for perfect execution at 45x earnings.
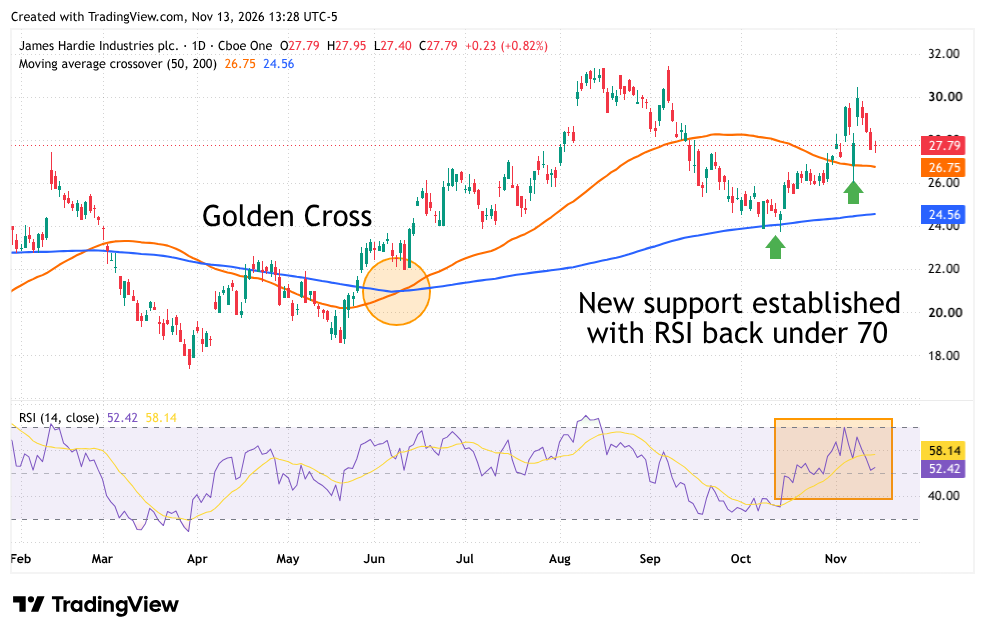
JHX shares have had the rockiest ride in 2026 of our three remodeling stocks, but it's still up more than 30% YTD and more than 10% in the last month alone.
A Golden Cross in July provided technical traders with some optimism, but momentum faded after a brief rally, and shares once again tested the 200-day moving average. The 200-day held, and the RSI broke back into bullish territory, signaling that the next leg of the rally can commence. Now shares are challenging the 50-day moving average; if support holds here, the rally will have a strong technical uptrend that would likely require a negative catalyst to break.
Before you consider Masco, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Masco wasn't on the list.
While Masco currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking for higher dividend income in 2027? Discover seven high-yield dividend stocks with attractive payouts, proven dividend histories and growth potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
