Walt Disney Today
$116.88 -1.83 (-1.54%) As of 11/17/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $92.18
▼
$122.72 - Dividend Yield
- 1.28%
- P/E Ratio
- 24.10
- Price Target
- $129.61
The Walt Disney Company’s NYSE: DIS Q4 results and guidance update offered investors reasons for optimism.
Results reflect the company's strategy under CEO Josh D’Amaro, whose focus is expanding experiences, capacity, and margins.
The report shows signs of strength, but the capital return increase may matter most. After previously suspending its dividend, Disney has restored the payout and now followed it with a 33% dividend increase. The $2 annual dividend, paid in two $1 installments, is the largest in Disney's history.
Disney Builds Momentum in Q4, Guides for Strength in 2027
Disney had a good Q4, even adjusting for the extra week. Reported revenue grew nearly 16% to $25.95 billion, outpacing consensus by about 3%, driven by strength across all segments. Entertainment, Sports, and Experiences all reported mid-teens revenue growth, although the extra week contributed to those gains, underpinned by new releases, park/cruise visitors, and expanding monetization of digital assets.
Operating leverage is the report's biggest strength. The company widened margins across the board, driving accelerated profitability in most categories. Sports also contributed to the improvement, with advertising, fees, and viewership rising. Viewership is a key detail, with ESPN networks recording their highest consumption since fiscal 2015, suggesting continued strength in audience engagement. The impact on earnings is substantial, with earnings before taxes up 71%, segment operating income up 43%, cash from operations up 51%, and free cash flow of $4.8 billion up 89% versus the prior year.
Guidance is a catalyst, setting the stage for milestone rallies as quarterly results are revealed. Management reaffirmed its outlook for double-digit adjusted earnings growth, more than two percentage points above consensus, and may be cautious on the estimate. Other key details include $11 billion in expected free cash flow, including accelerated growth investments, and $9 billion in share buybacks. The $9 billion is flat versus 2026 but still solid, worth about 4.4% of the mid-November market cap. Q4 and 2026 buyback activity shows a 2.7% full-year reduction, with activity accelerating to about 4% in Q4.
Disney Validates Analysts' Optimism: Fresh Highs Possible
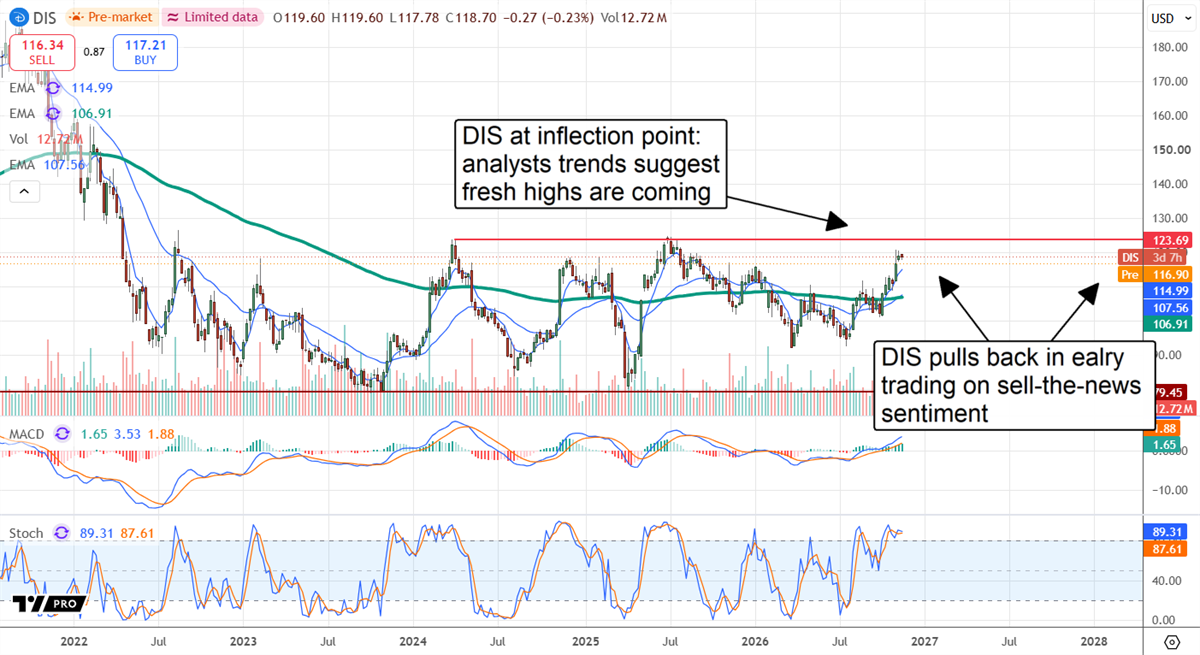
Disney’s Q4 wasn’t game-changing but may reinforce the optimism already reflected in analyst ratings. MarketBeat data shows 19 current ratings, a bullish bias within the Moderate Buy consensus rating, and an average price target implying modest single-digit upside. That could be sufficient for fresh highs, a significant move for technical investors. Moving to fresh highs would break DIS out of a multi-year trading range, potentially opening the door to a larger advance. In this scenario, the trading range magnitude suggests a measured-move target about $45 above the breakout level, or roughly 35% upside.
Valuation may also support the upside case. Trading at 17x forward estimates, Disney looks relatively inexpensive compared with the broad-market S&P 500. Assuming the guidance proves conservative and growth continues in subsequent years, upside potential could be greater, depending on time, cash flow, and capital return capacity.
Upside Risk Remains: DIS Institutional Buying Trends Are the Ones to Watch
Price action is iffy following the release, with shares fluctuating in early trading. The take, however, is that Disney’s news may have triggered a sell-the-news event, as prior price action revealed optimism. Up about 20% in the months before the release, DIS shares appeared positioned for a rally if a strong enough catalyst emerged. The risk for investors is that resistance at the range top could cap gains until next year, when more evidence of growth and margin strength becomes available.
Walt Disney MarketRank™ Stock Analysis
3.90889689209 of 5 stars- Overall MarketRank™
- 78th Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 9.0% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- Moderate
- News Sentiment
- 0.40
- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 7.65%
See Full AnalysisInstitutional activity is a factor to watch. The group reflects confidence, owning approximately 65% of the shares, and has accumulated on balance over the trailing 12 months, although some institutions reduced their holdings in the latest reported quarter. If institutional selling continues, DIS shares could struggle to break out of their range or sustain a breakout. Downside risks are also significant, with a potential support level near the range bottom, approximately 33% below recent prices.
Disney’s biggest risks include capital spending and cost-cutting. The company’s aggressive investment posture has helped drive traffic and could continue to do so with new attractions like Piston Peak National Park, but higher spending can pressure profits while the company tries to cut costs. Both efforts carry execution risks that could weigh on the stock. Recent releases, including Toy Story 5, have helped drive engagement and sales across Disney's businesses.
Before you consider Walt Disney, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Walt Disney wasn't on the list.
While Walt Disney currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
